Blue Diamond Growers Almond Market Report – November 13, 2026
Market Summary
Demand Drivers
- Year-to-date shipments reached 673.3 million pounds, up 11.4%, supported by another solid export month
- Domestic new sales increased 17.6% to 73.5 million pounds, demonstrating a rebound in activity
- India turned in another strong month at 52.3 million pounds
- Shipped + Committed remains ahead of last year at +2.9% YOY
Demand Constraints
- Export kernel demand lags last year by 15.6%
- Spanish origin competition is providing European buyers flexibility and an alternative supply source
- Buyers remain in a hand-to-mouth purchase approach globally
Supply Drivers
- Receipts reached 1.9 billion pounds, up 11.7%
- Uncommitted supply, up 15% YOY, provides nearby availability although the makeup of supply varies by variety and specification
- Harvest is largely complete, with huller/shellers now focused on processing remaining stockpiles
Supply Constraints
- Smaller kernels and lower moisture continue to reduce delivered kernel weights
- Large kernels remain limited across varietals
- Pollinizers continue to underperform which will continue to place downward pressure on outlook of overall crop size
Looking Ahead
October’s report presents a more balanced demand picture than September. Improved domestic shipments and bookings are encouraging, while softer export sales and concentrated inshell growth temper the headline shipment result. Tighter crop expectations remain supportive and could tighten availability later in the season. The timing and extent of that tightening will depend on sustained new sales, destination inventory clearance rates, and final crop receipts. Post-Diwali replenishment, Ramadan and Chinese New Year consumption along with subsequent restocking activity, and European first-half coverage along with remaining crop receipts will determine the next phase of the market.
Shipment Summary
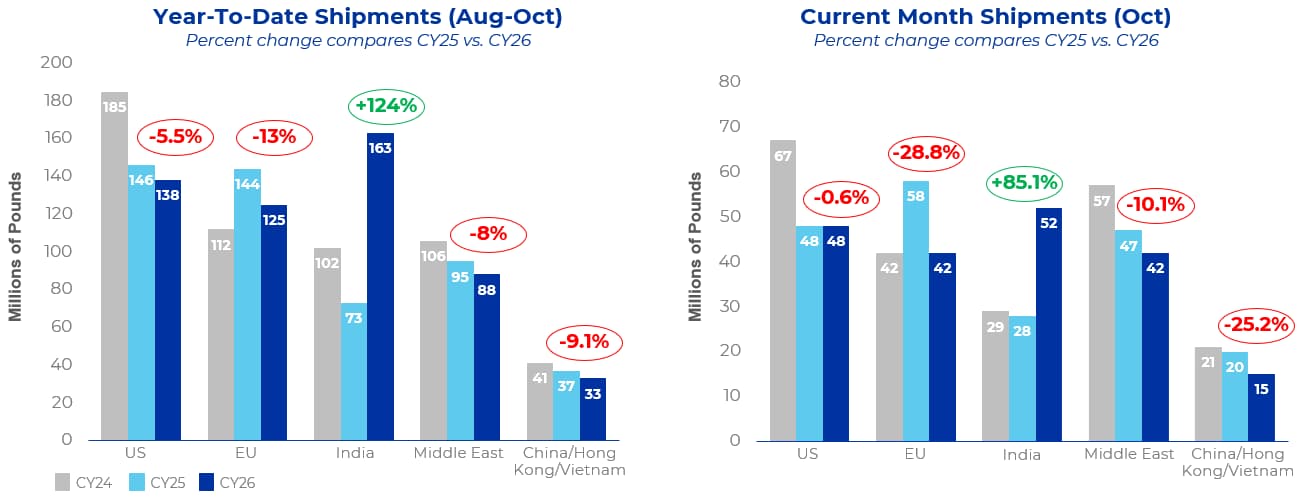
October shipments totaled 250.6 million pounds, flat to prior year. For the month, exports reached 202.7 million pounds, an increase of 0.8%, while the domestic market shipped 48 million pounds, a decline of -0.6% versus last year. Total domestic market shipments are pacing behind prior year by -5.5%; with strong exports at 16.8% ahead of last year’s pace, we continue to see the industry total shipments outpacing results from last year by 11.4% after three months of shipments.

Regional Dynamics
India: India received 52.3 million pounds in October, up 85.1%, bringing year-to-date shipments to 162.9 million pounds, an increase of 124%.
The strong October performance extends the early season inshell shipment momentum, although the pace of arrivals is beginning to shift the market’s focus toward downstream inventory absorption. With Diwali now behind us, the key indicators will be the rate of destination inventory clearance and the extent to which buyers return to the market with replacement orders.
China/Hong Kong/SE Asia: China/Hong Kong received 6.1 million pounds in October, up 62.5% versus prior year, bringing year-to-date shipments to 9.5 million pounds, up 50.2%. Vietnam received 9.2 million pounds, down 45% year over year, with year-to-date volume of 23.6 million pounds, down 21.6%. Combined China/Hong Kong/Vietnam shipments declined 25.2% in October. The market will closely watch the upcoming Asia-Pacific Economic Cooperation (APEC) Summit scheduled for November 18-19 where President Trump and President Xi are expected to engage in further discussion revolving around a potential trade deal.
Europe: Total European shipments reached 41.6 million pounds in October, down 28.8%. Year-to-date volume stands at 124.9 million pounds, down 13.3%. Western Europe shipped 39.2 million pounds, down 27.3%, with year-to-date volume down 12.3%. The decline deepened month over month, led by Spain and Italy, while Germany and the Netherlands increased. Spanish-origin availability remains a competitive alternative for local buyers. Many buyers in Europe are only lightly covered for calendar year Q1 so booking timing will be closely monitored in the coming weeks.
Middle East & Pakistan: Middle East shipments, inclusive of Pakistan, totaled 54.3 million pounds in October, with year-to-date volume of 116.9 million pounds. Pakistan remained a major growth destination, receiving 11.8 million pounds for October, compared with 1.9 million a year earlier. Year-to-date shipments to the country reached 28.9 million pounds, up 360.3%. These movements reinforce changing trade flows and inventories as well as end-market demand. It is important to note that while Pakistan is reported separately from the Almond Board’s Middle East regional grouping, much of the product destined for the country will find its way into the region’s end markets.
Domestic: October domestic almond shipments totaled 47.9 million pounds, down 0.6% year over year. Although this marked the third consecutive month of decline, October was more in line with expectations, and the market now trails last year by 5.5%. New domestic sales provided a bright spot, increasing nearly 21% year over year and helping narrow the percent commitment deficit by roughly half. Current commitments continue to provide a base of booked business to support shipments through year-end. Looking ahead, retail sales performance during November and December will be a key indicator of demand as companies balance inventory levels and production schedules with holiday sales. Buyers are likely to remain measured, monitoring demand trends and aligning purchases with near-term needs.
Commitments
Total committed shipments stand at 526.2 million pounds, lagging prior year by -6.3%. Export commitments stand at 340 MM pounds (-6.2% from PY) and domestic are at 186.2 MM lbs. (down -6.4% from PY). New sales for October were 247.7 million pounds with exports adding 174.2 million pounds of coverage and domestic adding 73.5 million pounds. Faster pace of receipts has resulted in uncommitted inventory being up by 148 million pounds at 1,130 billion pounds total for now. The table below shows commitments and sales in both domestic and export markets.
| Region | Commitments YTD | vs. PY | Sales YTD | vs. PY |
| Global | 526.2 | -6.3% | 650.8 | -2.19% |
| Domestic | 186.2 | -6.4% | 139 | -23.1% |
| Exports | 340 | -6.2% | 511.8 | +5.6% |
Volume reported in millions of pounds
Crop
2026 crop receipts to date total 1.89 billion pounds, running 11.7% ahead of the same point in 2025. The 2026 harvest is now largely complete. An early start, a smaller crop, and favorable weather made for a fast season reflected in the pacing of the receipt number to date. Huller/sheller operations are now working through stockpiles. Most expect to finish before Thanksgiving, and larger operations by mid-December.
Receipts continue to show small kernel sizes across all varieties and lower moisture than 2025, both of which impact kernel weight. Pollenizer yields fell below expectation, mainly because Butte/Padre and California varieties performed poorly. These combined factors point toward a crop range of 2.56 to 2.62 billion pounds with a midpoint of 2.59 billion pounds with indicators pointing towards the lower end of the range. Reject levels are generally the lowest in several years. The exceptions are plant bug damage (brown spot) in Independence and higher navel orangeworm losses in pollenizer varieties after the third flight. Any additional insight into crop size potential will be reflected in the next Market Report.
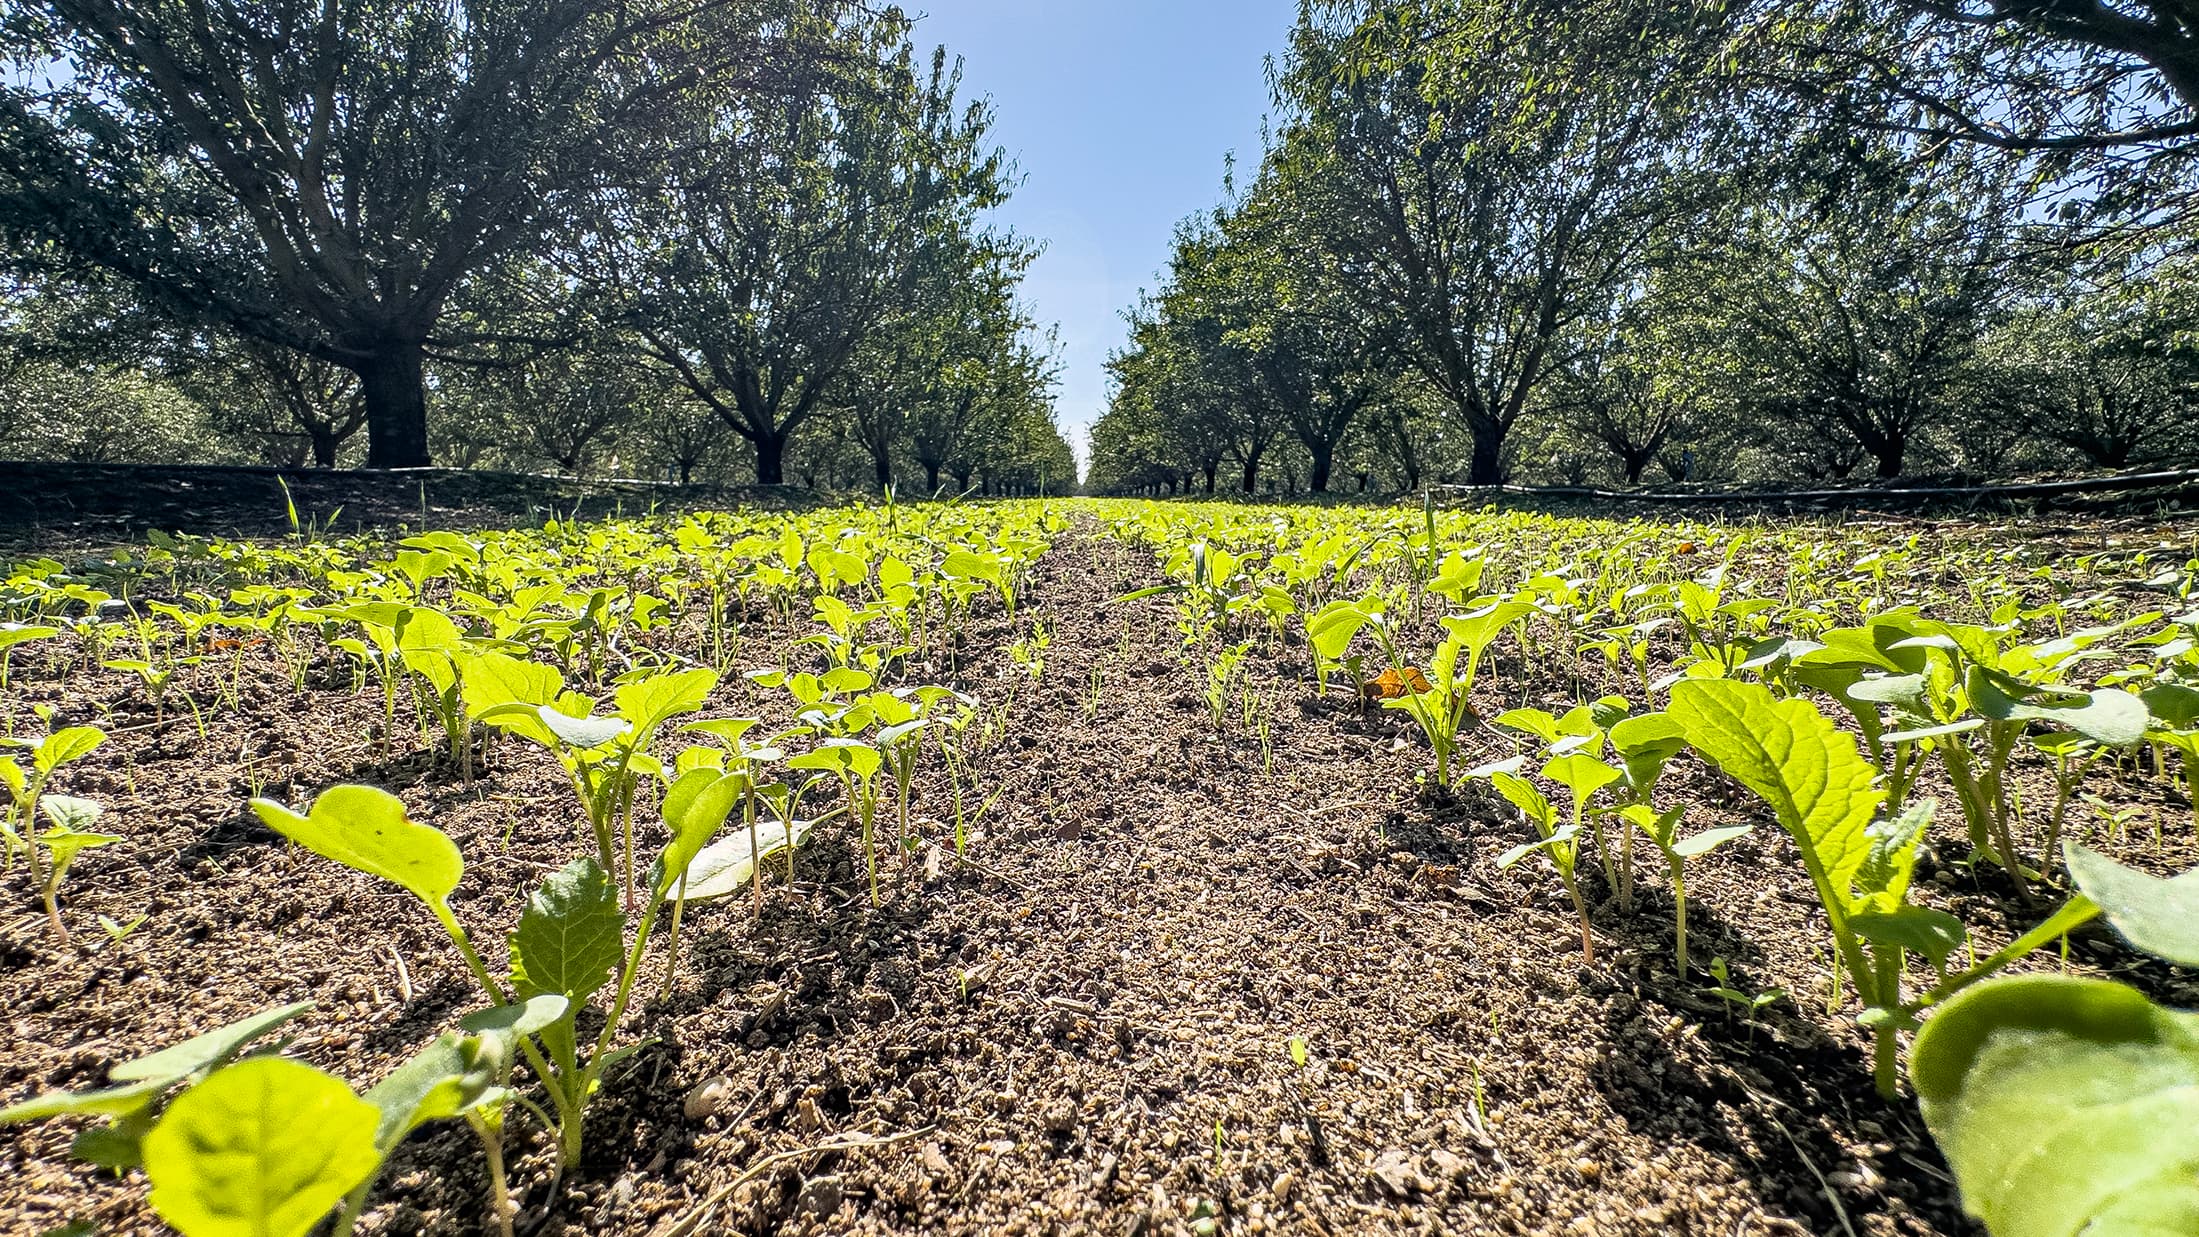
With low temperatures during the night, the trees are starting to go into dormancy for the winter to start preparing for bloom in a few months. El Niño and the impact it may have on the 2027 crop is top of mind for many growers. Firming grower returns are reflected in increased post-harvest activities including nutrition and cover crop plantings despite increased production costs. The 2026 LandIQ final acreage estimate will be released later this month providing a first glance at crop potential in 2027.
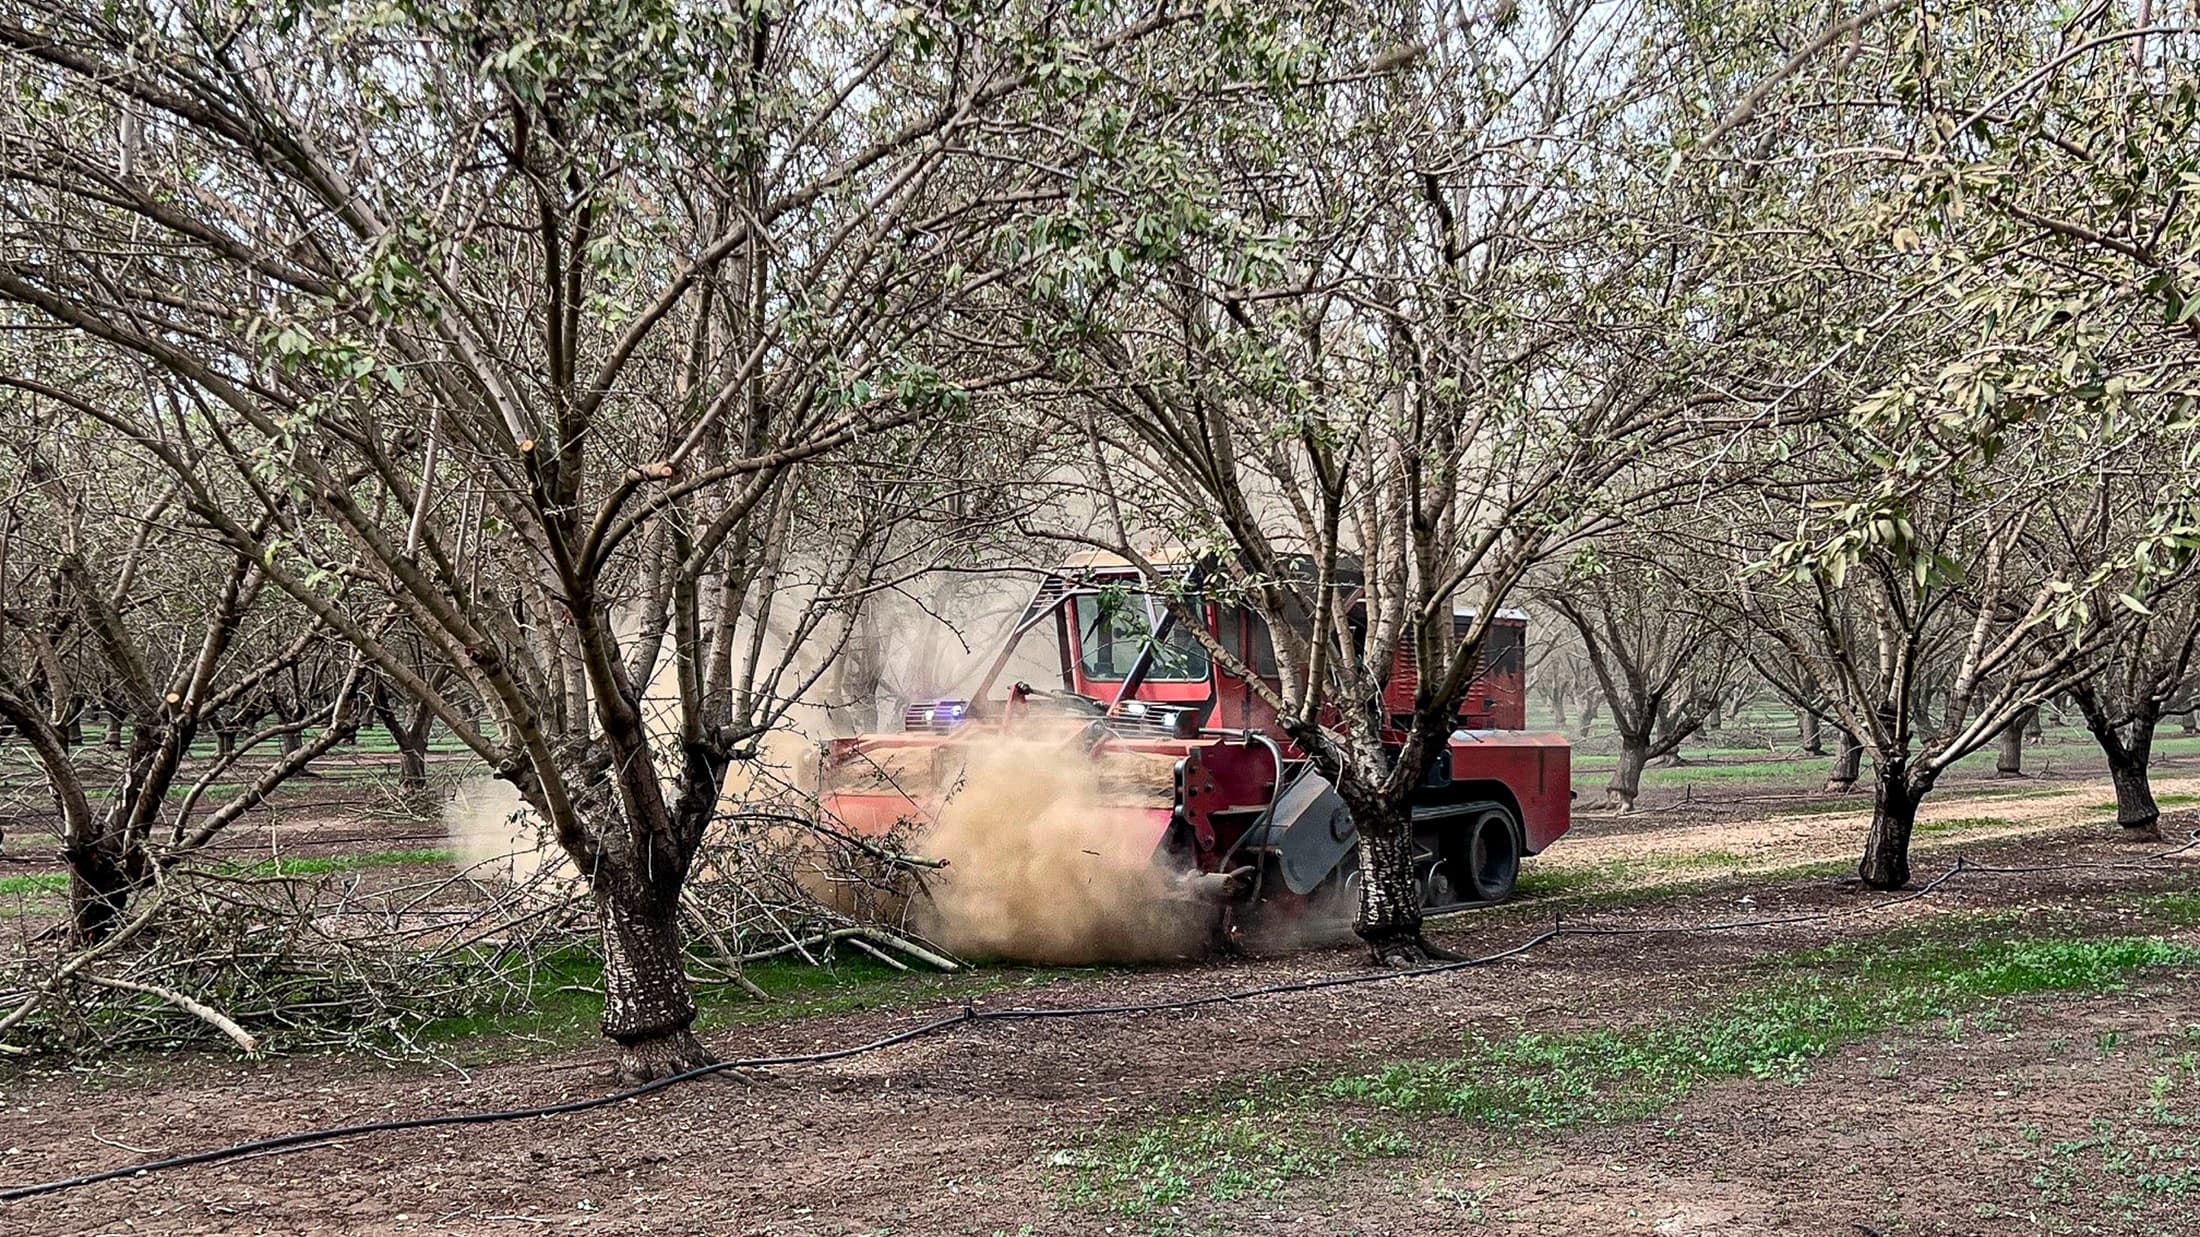
Photo courtesy Mel Machado, Chief Agricultural Officer.